What to know
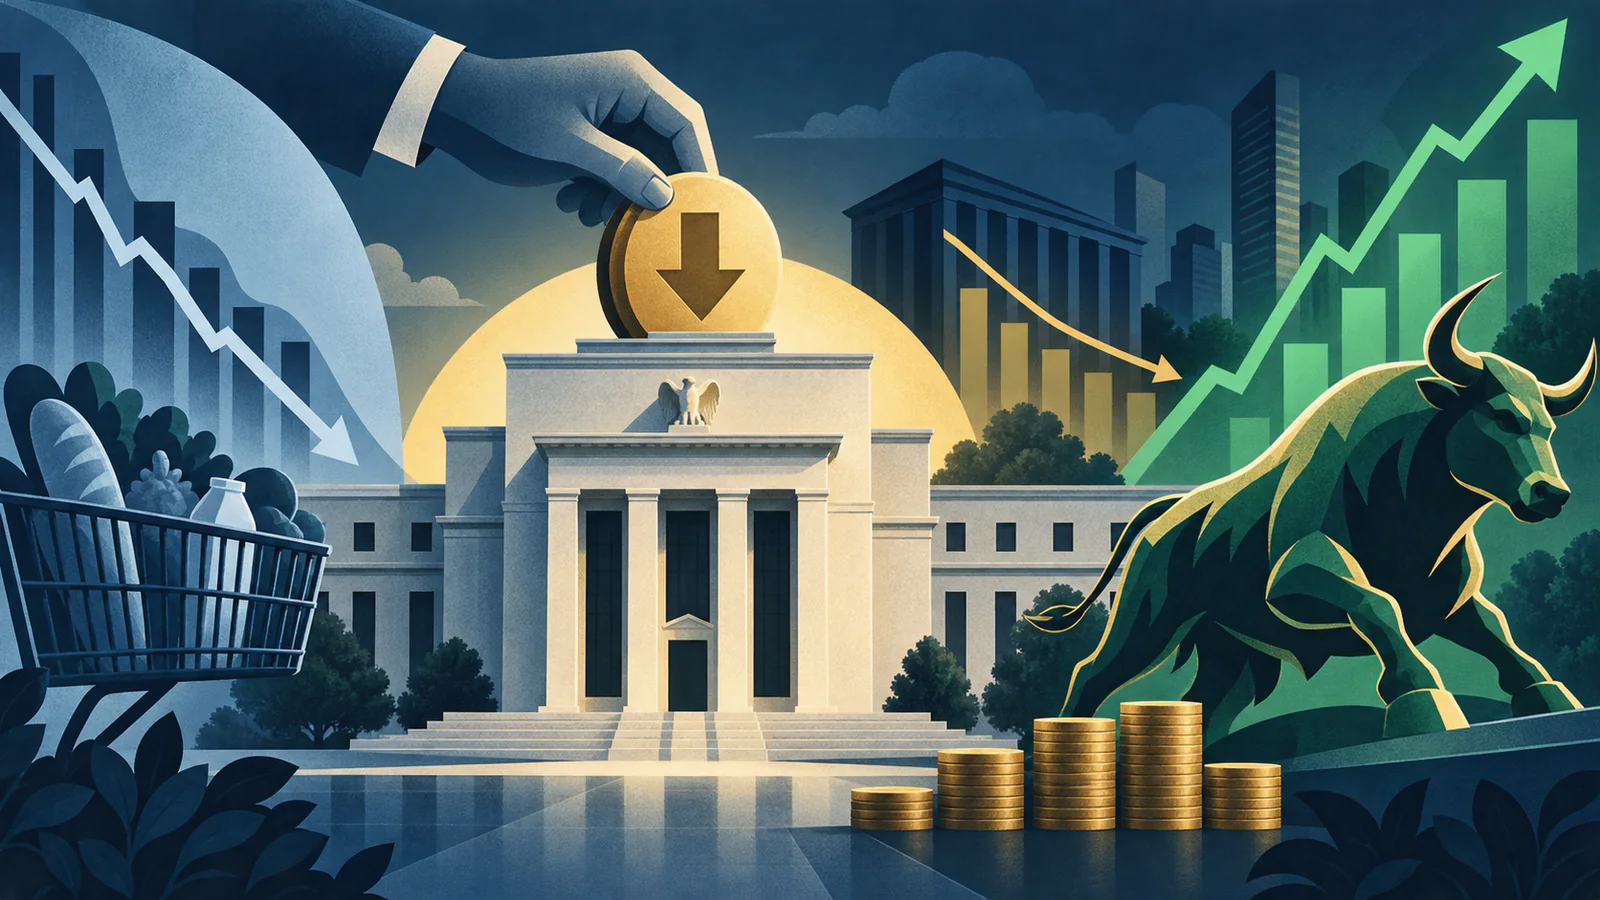
A broad-based moderation in consumer price data has solidified investor optimism for a soft landing, pulling benchmark bond yields lower and fueling a broad rally across rate-sensitive equities and cyclical industries.
Further reading and standardsNEW YORK — Financial markets across Wall Street experienced a broad-based surge as latest government inflation data arrived softer than forecasted, giving institutional investors concrete reassurance that the Federal Reserve's restrictive monetary policy is successfully deflating price pressures without stalling broader economic momentum. Benchmark equity averages rallied across the board, with the S&P 500 advancing 1.2% and the small-cap Russell 2000 jumping 2.1% as traders aggressively expanded bets on interest rate reductions.
What Happened: Comprehensive Disinflation Across Goods and Services
The latest economic metrics confirmed that disinflation is no longer confined to volatile commodity and used vehicle categories, but has firmly taken root across sticky service sectors:
Core consumer prices expanded at their slowest annualized rate in three years, bolstered by moderating residential rent indexes, declining transport services, and stable medical care costs. Economists at major investment banks noted that three-month annualized core PCE has dropped into close alignment with the central bank's official 2.0% objective.
Yield Curve Dynamics: Relief for Borrowers and Real Estate
The fixed-income market experienced an immediate recalibration following the inflation release:
- Treasury Yield Compression: The 2-year Treasury yield, closely tied to federal funds expectations, fell 12 basis points to 3.94%, while the 10-year yield dipped to 4.11%.
- Mortgage Rates Dip: Average 30-year fixed home loan rates retreated toward 6.1%, offering much-needed affordability relief to prospective homebuyers and mortgage originators.
- Corporate Debt Issuance: Investment-grade and high-yield corporate borrowers rushed to price new bond offerings, taking advantage of compressed credit spreads to refinance short-term debt maturities.
The Soft Landing Narrative: Economic Growth Defies Recession Fears
What distinguishes the current market backdrop from previous easing cycles is that rate cuts are being contemplated alongside resilient macroeconomic growth rather than an impending downturn:
U.S. gross domestic product continues to expand at a healthy 2.3% annualized clip, supported by high consumer savings buffers among upper-income brackets and sustained corporate investment in automation and cloud infrastructure. This "Goldilocks" backdrop—not too hot to rekindle inflation, not too cold to trigger job losses—has driven equity risk premiums lower.
What to Watch Next: Central Bank Forward Guidance and Jobs Reports
Market participants now turn their focus to the upcoming slate of Federal Reserve communications and primary labor data:
Speeches by FOMC governors in the coming weeks will reveal whether the central bank is prepared to shift its formal policy statement toward an explicit easing bias. Continued moderation in wage growth and nonfarm payroll additions in the 150,000-to-180,000 range will be critical to keeping the soft-landing rally on track.
Further reading
Use these official collections to explore the subject and confirm time-sensitive figures against the dated record.